Looking for the latest information on Binomial Tree? We've compiled comprehensive data, records, and insights about Binomial Tree.
Core Information
Explore the primary sources for Binomial Tree.
Developments
Stay updated on Binomial Tree's latest milestones.
FIN 376: Binomial Option Pricing and Delta Hedging
Binomial Interest Rate Trees Explained | CFA & FRM
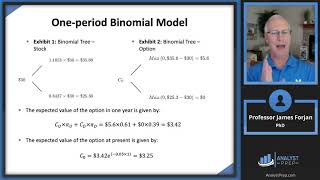
CFA Level I Derivatives - Binomial Model for Pricing Options
Two Step Binomial Tree - European Call
6.1 Binomial Trees | Properties with Proof | Introduction | Advanced Data Structures
Pricing an American Option: 3 Period Binomial Tree Model
Data Structures in Typescript #17 - Binomial Heap Introduction
Binomial Trees | Algorithms
Options pricing video 1- Binomial method - single time period
Pricing Derivatives with One Step Binomial Trees
Binomial Option Pricing Model || Theory & Implementation in Python
Full Guide
Data is compiled from public records and verified media reports.
Last Updated: September 21, 2026
Future Outlook
For 2026, Binomial Tree remains one of the most searched-for information profiles. Check back for the latest updates.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
00:00 Introduction to Binomial Model 01:33 Constructing a This playlist/video has been uploaded for Marketing purposes and contains only selective videos. For the entire video course and ... In this comprehensive video, we delve into the intricacies of the Ryan O'Connell, CFA, FRM explains This is an excerpt from our comprehensive animation library for CFA Level I candidates. For more materials to help you ace the ... This video prices a European call option on a two step In this video, I will cover the following : What is a We price an American put option using 3 period Data structures playlist: youtube.com/playlist?list=PLn4fTSbSpY5cL4_0MP83wq5khbmG3IKKd Code repository: ... So the binomial t b naught consists of a single node this is the node this is the three d naught right this is the We discuss how to replicate an financial derivative using a Today I will introduce the Theory of the Binomial Asset Pricing Model and show how you can implement the